

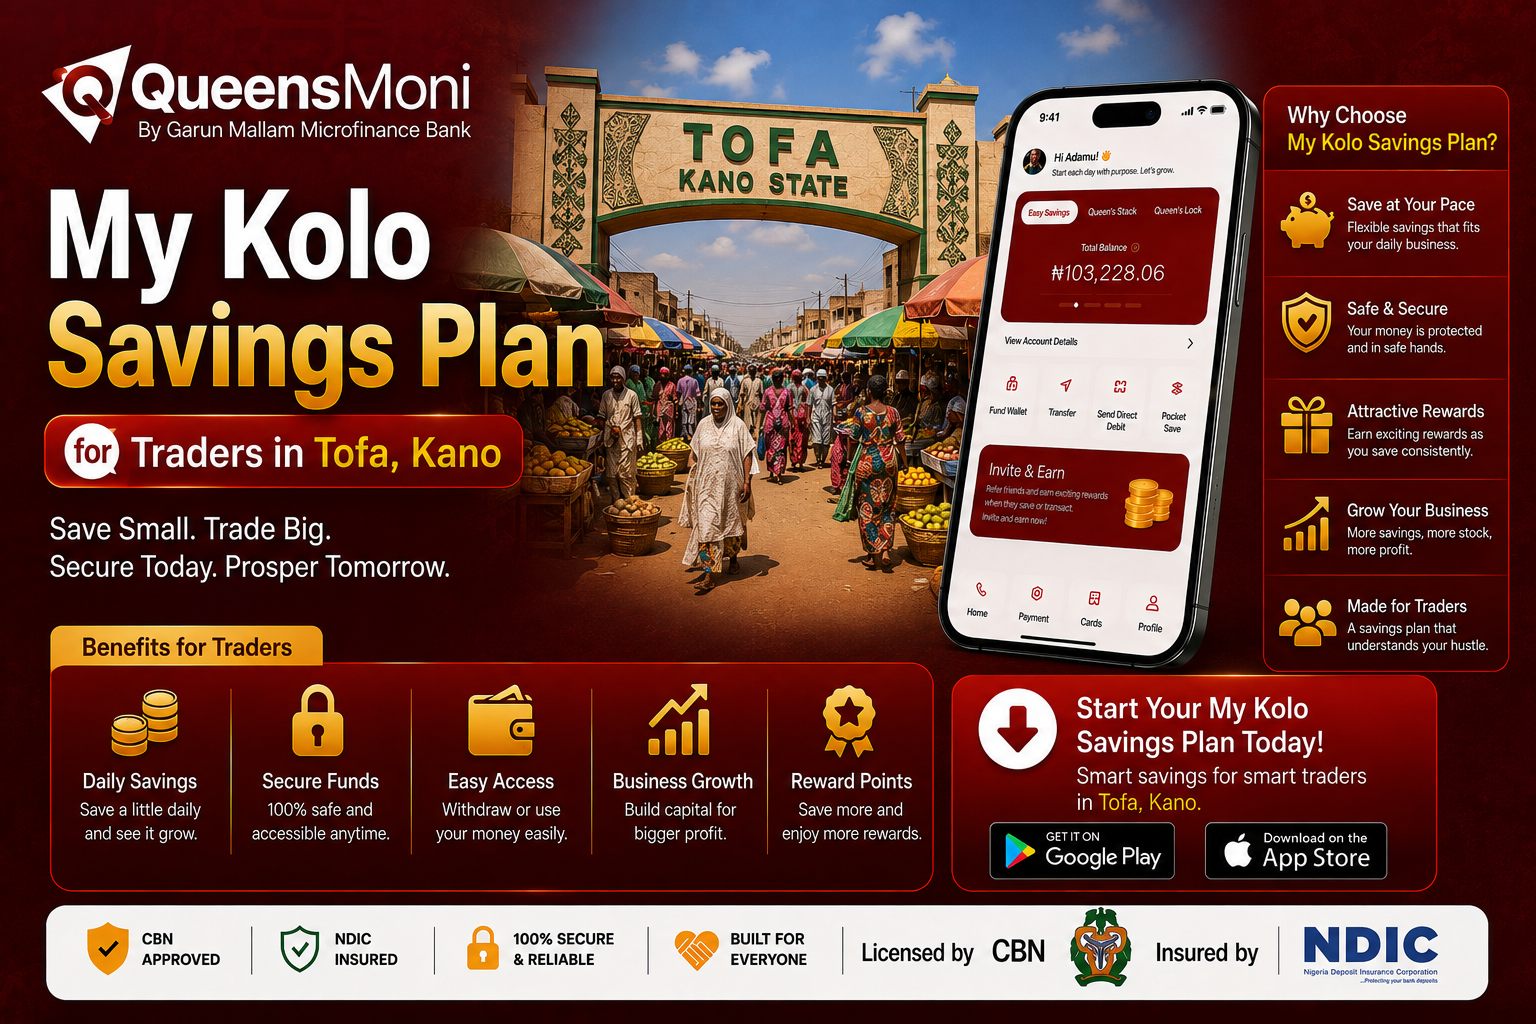
Tofa is one of Kano State’s agrarian local government areas, and if you trade there, you already know the rhythm of the place better than any outsider could explain it. Market days tend to follow the surrounding farming calendar. A busy harvest season means more buyers with more money to spend, and a quiet stretch between seasons means slower sales and tighter margins. That kind of income, uneven, tied to the land, arriving whenever it arrives rather than on a fixed date, is exactly what the My Kolo savings plan from Queensmoni was built to handle.
This is a proper, detailed walk-through of how My Kolo actually works, why it fits Tofa’s trading pattern specifically, how it stacks up against the bigger national savings apps, and exactly what to do if you want to start using it today.
Why standard savings advice doesn’t really work for a Tofa trader
Open any generic article about saving money, and you’ll usually find the same advice repeated: pick a fixed amount, save it every month, don’t touch it. That’s fine in theory, but it assumes something that simply isn’t true for most traders in Tofa, which is that your income arrives in predictable, equal chunks. It doesn’t. A strong market day tied to harvest season might bring in several times what a quiet weekday brings, and there’s no guarantee next month looks anything like this one.
This mismatch is a big part of why so many traders who genuinely want to save end up not doing it in any structured way. The tools built for salaried income simply don’t bend to fit trading income, so people either save informally, which works to a point but doesn’t earn interest and is easy to dip into, or they don’t save at all beyond keeping some cash aside. My Kolo exists specifically to close that gap.
What My Kolo actually is, in plain terms
My Kolo is a structured savings product that runs on auto-debit, but unlike a lot of savings tools, it doesn’t force you into one rigid monthly figure. It’s built around smaller, more frequent contributions, the kind of pattern that fits a trader’s daily or weekly sales far better than a traditional bank account ever could.
A few specifics are worth understanding clearly before you get started. It currently earns around 15% interest per year on whatever balance you’ve built up, which is a genuinely meaningful return if you’re consistent with it over time. There’s also an important condition around early withdrawal: if you take your money out before the date you originally agreed to when setting up the plan, you lose 25% of the interest that had accrued up to that point. This isn’t a technical glitch or an unfair penalty; it’s a deliberate part of the design. The whole point is to make casual, impulsive withdrawals genuinely uncomfortable so that the money you’ve committed to saving actually stays saved rather than slowly leaking back out for small, unplanned expenses.
It also works particularly well when it’s tied to a specific goal rather than just vague, general saving. Restocking ahead of the next big market day tied to harvest timing, building capital toward expanding into a second stall or a wider range of goods, or simply building a cushion to get through the quieter months between harvests—all of these give the plan a clear purpose that makes it easier to stick with.
How this compares to PiggyVest and Cowrywise
If you’ve looked into savings apps at all, you’ve probably come across PiggyVest and Cowrywise at some point, since both are widely advertised and used by millions of people across Nigeria. PiggyVest is known for making automated saving simple, letting you set a target and a schedule and largely forget about it. Cowrywise leans more toward mutual funds and structured investment products, popular among salaried professionals who want their savings doing a bit more than just sitting in an account.
Both are legitimate, well-built platforms. The issue, if you’re trading in Tofa specifically, is that neither was really designed around your kind of income. They’re national products built with a fairly generic, often salaried, and urban user in mind. If you try to force a trading income into their typical monthly savings structure, it can work, but it often feels like you’re fighting the tool rather than being helped by it.
My Kolo’s entire design starts from the opposite assumption: that income is going to be irregular, and the product should adapt to that rather than expecting you to adapt to it.
Getting started with My Kolo
The actual process of signing up is simple, and none of it requires traveling to central Kano. You’ve got a few options depending on what’s most convenient. You can go directly to queensmoni.com from a browser on your phone or computer. If you’re using an Android phone, the app is available for download on Google Play. And if you’re on an iPhone, you’ll find it on the Apple App Store as well.
Wherever you register, you’ll need a valid means of identification, whether that’s a national ID, voter’s card, driver’s license, or international passport, along with your bank verification number. This is a standard requirement across any regulated financial platform operating in Nigeria, not something unique to Queensmoni, so don’t be surprised by it.
Once you’re registered and verified, select My Kolo from the available savings products, and think carefully about a realistic deposit pattern. Base it on your actual average income across good and bad market days combined, not on your single best day. Setting the bar too high early on is one of the most common reasons people abandon a savings plan within the first couple of months.
Practical habits that actually make a difference
A few things separate traders who stick with My Kolo long enough to see real growth from those who give up early.
Save right after you sell, ideally before the cash gets absorbed into daily running costs or small personal spending. Money that sits in your pocket for even a day tends to shrink before you get around to setting any of it aside.
Base your savings target on a genuine average across your whole trading cycle, including the slower days and the quieter seasons, rather than assuming every day will look like your best one.
Give the plan a specific purpose rather than a vague one. “I’m saving to restock ahead of the next big market day” is far easier to stay committed to than simply “I’m trying to save money.”
And treat the early withdrawal penalty as something working in your favour, not against you. It exists specifically to protect you from your own worst weeks, the ones where dipping into savings feels tempting but would undo months of consistent progress.
Beyond My Kolo: What else is available if your needs grow
While My Kolo is the natural starting point for most traders, Queensmoni offers a couple of other products worth knowing about as your savings grow. Queens Lock works similarly to My Kolo in that it’s an auto-debit savings plan, but it’s built for money you want completely out of reach until a specific, longer-term goal is met, useful if you know you need a firmer commitment than My Kolo’s structure provides.
Once you’ve built up a genuinely large balance, whether through consistent My Kolo contributions or a particularly strong trading season, moving a portion into a fixed deposit can make sense too. Fixed deposit rates improve with both the size of the deposit and how long you’re willing to commit it for, running from 90 days up to a full year, making it a natural next step once My Kolo has done its job of building the initial habit and balance.
Frequently asked questions from traders in Tofa
What exactly is the My Kolo savings plan?
It’s a flexible, auto-debit savings product from Queensmoni, earning roughly 15% interest annually, specifically designed for people who save smaller amounts frequently rather than one large fixed sum every month.
What actually happens if I need to withdraw before my agreed date?
You’re able to withdraw the money, but you’ll forfeit 25% of the interest that had built up to that point. It’s a real cost rather than a strict block, meant to discourage casual, impulsive withdrawals while still leaving the money accessible if you genuinely need it.
I don’t have a fixed income as a trader. Does My Kolo actually work for me?
Yes, that’s precisely the situation it was built for. Rather than demanding a fixed monthly amount, it’s designed around flexible, irregular deposits that fit trading income much more naturally than a traditional savings account would.
Is Queensmoni available on iPhone or only on Android?
It’s available on both. You’ll find it on the Apple App Store as well as on Google Play.
How is My Kolo different from Queens Lock?
Both run on auto-debit, but My Kolo is more flexible around deposit amounts and timing, while Queens Lock is built for a firmer, more committed savings goal you don’t intend to touch until it’s reached.
Is my money actually safe if I save through Queensmoni?
Queensmoni is backed by a licensed microfinance bank, which covers the regulatory side of things. As with any financial platform, it’s worth confirming current licensing details directly before committing a significant amount of money.
The bottom line for Tofa’s trading community
If you’ve struggled to make saving stick as a trader in Tofa, there’s a decent chance the problem was never discipline; it was that the tools available simply weren’t built for how your income actually arrives. My Kolo starts from a completely different assumption, that your money comes in unevenly, tied to market days and harvest seasons, and builds the entire product around that reality rather than expecting you to force your income into a shape it was never going to take.
Ready to give it a try? Visit Queensmoni or download the app on Google Play or the Apple App Store and start your My Kolo savings plan today.