

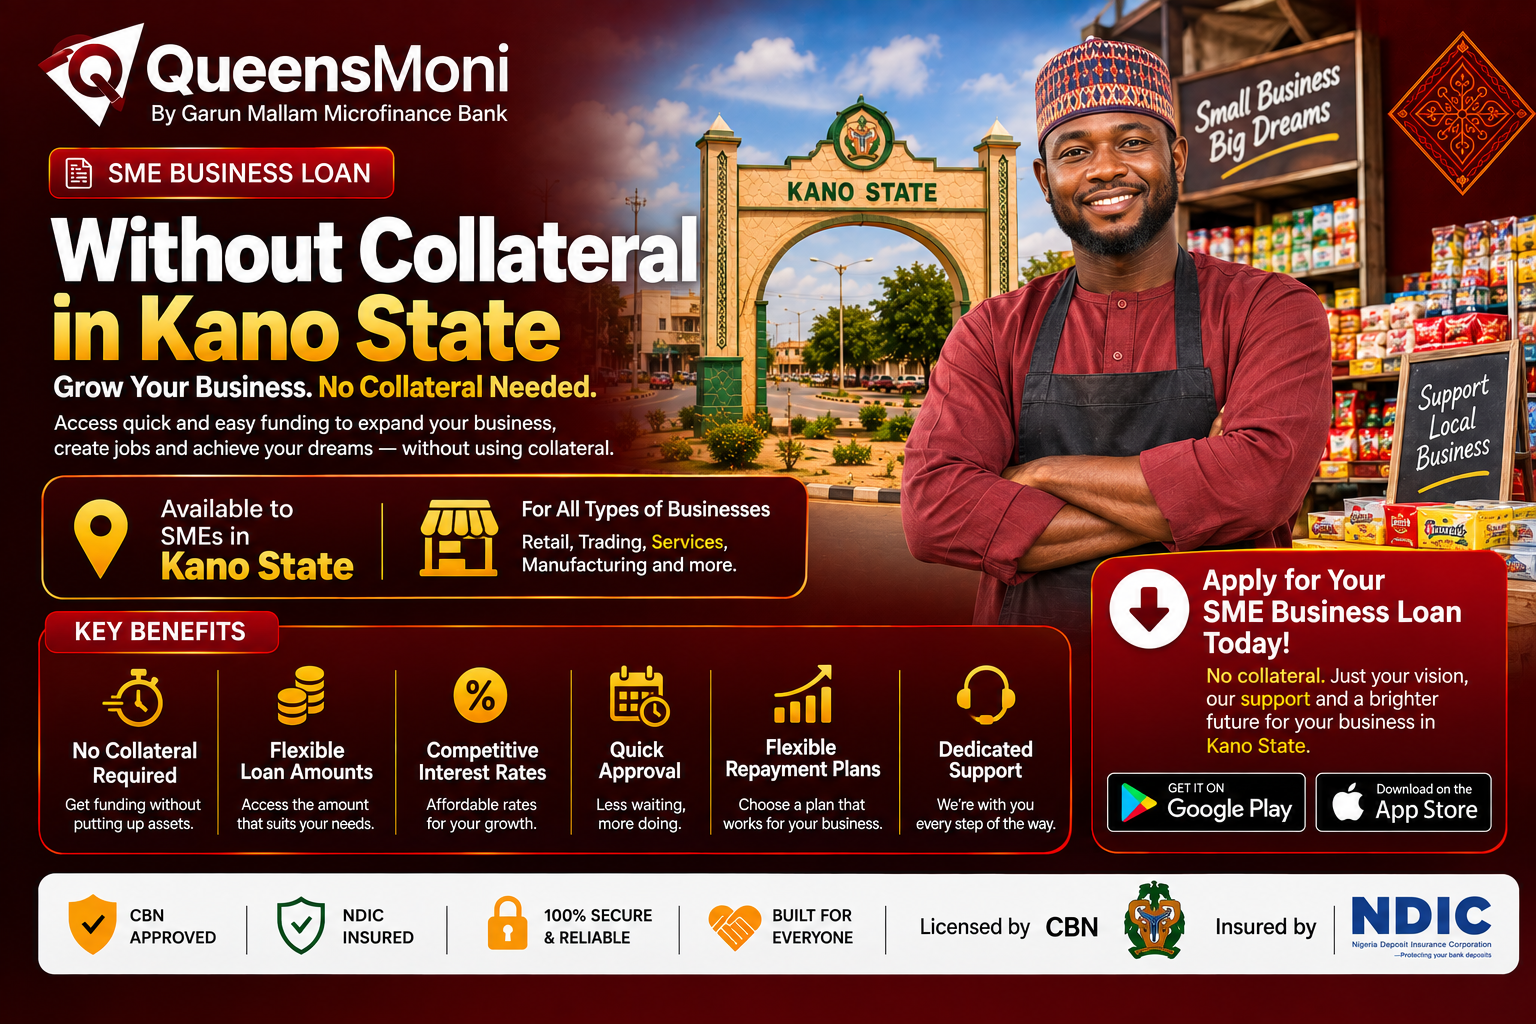
If you’ve ever tried to get financing from a traditional bank for a small business in Kano State, you already know the usual answer: bring collateral- land, property, or some kind of formal asset the bank can hold against the loan. For most small traders, shop owners, and artisans, that requirement alone rules out the option entirely, not because the business isn’t viable, but because collateral of that kind simply isn’t something most small business owners have sitting around. This is exactly the gap that has pushed more entrepreneurs across Kano State toward SME financing that doesn’t demand fixed collateral at all.
Why collateral-based lending doesn’t fit most small businesses
Traditional lending was built around a fairly narrow assumption: that a borrower has formal assets worth pledging against the loan amount. That works reasonably well for larger, more established businesses, but it excludes the vast majority of small business owners in Kano State, whose real assets are things like inventory, customer relationships, and years of trading experience, none of which fit neatly into a bank’s collateral checklist.
The alternative that’s emerged across Nigeria’s SME financing space relies on different signals instead, things like transaction history, savings patterns, and a demonstrated track record of financial discipline. This shift matters enormously for small business owners in Kano State, since it opens up financing to people who were previously locked out simply because they didn’t own a piece of property to pledge.
How collateral-free SME financing actually works
Instead of asking what you can pledge, this kind of financing generally asks what your business actually looks like in practice. Lenders want to understand your transaction patterns, whether you’ve demonstrated consistent saving behaviour, and whether you have a clear, specific plan for how the financing will be used and repaid.
This is part of why building a savings history matters even before you need financing. A consistent pattern of saving, through something like a structured savings plan, demonstrates exactly the kind of financial discipline that supports a collateral-free financing conversation. It’s evidence, in a sense, that substitutes for the physical collateral a traditional bank would otherwise require.
Where Queensmoni fits into this picture
It’s worth being clear about something upfront. Queensmoni’s core identity is built around savings and investment; products like My Kolo, Queens Lock, and Fixed Deposit sit at the centre of what it offers, and these are fully digital, app-based products you can start using in minutes. Structured SME and business loans exist as a secondary, more relationship-based offering, aimed specifically at small business owners who need working capital or business financing, but this isn’t an instant, algorithm-driven loan product available with a single tap in the app.
That distinction actually works in favour of a genuinely collateral-free approach, since a more considered, relationship-based process allows a lender to look at your actual business situation rather than relying purely on rigid, automated criteria. If you’ve built a savings history with Queensmoni through My Kolo, that track record becomes a meaningful part of the picture when discussing financing needs.
What this kind of financing is typically used for
Small business owners across Kano State generally seek out collateral-free financing for a handful of recurring needs. Restocking inventory ahead of a busy season, when having sufficient stock directly determines how much revenue the business can capture. Covering the working capital gap between paying suppliers and collecting from customers, one of the most persistent cash flow challenges for small traders anywhere. Expanding into a second location, a wider product range, or additional equipment once an initial business concept has proven itself. And covering short-term operational costs during a period of unusually high demand or an unexpected opportunity.
Being specific about your actual need, rather than requesting financing for vague, undefined “business purposes,” makes any financing conversation far more productive and improves your chances of a genuinely useful outcome.
Comparing this approach to national fintech lenders
If you’ve researched business financing before, names like OPay, PalmPay, Kuda, and Moniepoint have probably come up, particularly Moniepoint, which has built a real reputation around SME-focused tools and agency banking. These platforms offer real value, particularly for payments, transfers, and, in some cases, instant, algorithm-based lending products aimed at a broad national audience.
What Queensmoni offers instead is a more deliberate, relationship-based approach specifically for business financing, combined with a genuine savings and investment ecosystem that can actually strengthen your position over time. Building consistent savings habits alongside pursuing financing tends to produce a stronger overall financial picture than relying on financing alone.
How to approach this as a small business owner in Kano State
Get specific about your actual need before reaching out. A precise, well-reasoned request, tied to a concrete business activity, is always more productive than a vague ask for general capital.
Start building a financial track record before you need it. Even a few months of consistent saving through a product like My Kolo demonstrates real financial discipline, and starting this early, rather than right when you need financing, puts you in a stronger position.
Reach out through queensmoni.com or the app, available on both Google Play and the Apple App Store, to understand current requirements and the actual process involved, since specific terms and criteria can be reviewed and updated over time.
Prepare basic documentation in advance. A valid means of identification and your bank verification number are standard requirements across any regulated financial platform in Nigeria, and evidence of your business activity, whether transaction history or existing savings patterns, will likely be part of the conversation.
Be realistic about how much you request and how you’ll actually repay it. A smaller, well-matched amount that you can comfortably service tends to work out far better than borrowing the maximum available and hoping your business grows into the repayment.
What to watch out for
Always ask for the full picture of what you’ll repay, not just the headline interest figure. Processing fees, insurance add-ons, and penalty structures can meaningfully change the actual cost of financing.
Match your expected repayment pattern to how your business genuinely generates income. A business with seasonal peaks and quiet stretches needs a repayment structure that accounts for that reality, not one that assumes steady income every single month.
Avoid taking on multiple financing commitments for the same underlying need. Stacking obligations from different sources tends to create more strain than the combined capital is actually worth.
And keep building savings alongside any financing you take on. A consistent habit, through something like My Kolo, strengthens your overall financial position regardless of whether you’re actively borrowing at any given moment.
Frequently asked questions
Is it actually possible to get business financing in Kano State without collateral?
Yes, though the criteria shift toward things like transaction history, savings patterns, and a clear, specific business need rather than physical assets pledged against the loan.
Does Queensmoni primarily offer loans, or is it something else?
Queensmoni’s core focus is savings and investment, through products like My Kolo, Queens Lock, and Fixed Deposit. Structured SME loans exist as a secondary, relationship-based offering for small business owners specifically.
Does having a savings history actually help when seeking financing?
Generally, yes. A demonstrated pattern of consistent saving shows the kind of financial discipline that meaningfully supports any conversation about business financing.
Is there an app for reaching out about SME financing?
Yes, the Queensmoni app is available on both the Apple App Store and Google Play.
How is this different from an instant loan app?
Rather than an automated, algorithm-driven process, this is a more relationship-based approach, focused on genuinely understanding your business situation rather than issuing funds based purely on automated criteria.
Is this a safe and legitimate way to seek financing?
Queensmoni is backed by a licensed microfinance bank, covering the regulatory side of things. As with any financial arrangement, it’s worth confirming current terms directly before committing to anything.
Final word
Collateral-free SME financing has opened real doors for small business owners across Kano State who were previously excluded from traditional lending simply for lacking formal assets to pledge. Approached deliberately, with a specific need in mind and a genuine savings foundation built alongside it through products like My Kolo, this kind of financing can be a real tool for growth rather than just a stopgap.
To explore your options or start building your savings foundation, visit Queensmoni, or download the app on Google Play or the Apple App Store.